Menu

9 Best Mortgage Brokers in Zurich

Buyers in Zurich can take a mortgage straight from their bank or go through a broker who compares banks, insurers and pension funds. Brokers range from online platforms with advisers on call to independent financial planners who look at pension savings, taxes and amortisation at the same time, and they are paid in different ways: lender commissions, platform fees or hourly rates.

This guide sets out how each one works, how many lenders it compares where it says so, how it charges and who offers advice in English.

How this guide is ordered

We researched mortgage brokers in Zürich and narrowed them down to those with genuine expertise, strong reviews and complete contact details.

Certain businesses pay to be featured more prominently.

Top 3Full listMapHow to choose

Compare 9 local options

MY HYPOTHECA AG, Zürich#1
What stands out
  • Mortgage and pension advice together

  • Free first consultation

  • Support after signing

MY HYPOTHECA AG

5.0227 reviews
Josefstrasse 214a, 8005 Zürich, Switzerland
Best for
First-time buyers

A fit for first-time buyers who want the financing strategy explained before any offers are negotiated. The firm works in four steps: an analysis of your finances, a financing strategy, negotiation with lenders and the final choice. It is not tied to any bank and combines mortgage advice with pension planning. After signing, it stays on as the contact for later adjustments and refinancing. The first consultation is free, and the website has English pages.
HYPOTHEKE.ch, Zürich#2
What stands out
  • Same commission whichever lender

  • Surplus commission paid back

  • English version of the site

HYPOTHEKE.ch

4.9290 reviews
Lintheschergasse 13, 8001 Zürich, Switzerland
Best for
Comparing rates online first

Suits buyers who like to compare rates online before talking to anyone. The platform shows offers from more than 30 banks, insurers, pension funds and investment foundations, and specialists are available for a one-to-one consultation. It charges a platform fee that is offset by the lender's commission, and any surplus is paid back to the client. The company is owned by its three founders rather than by a bank or insurer. The website has an English version.

HYPOPARTNER GmbH, Zürich#3
What stands out
  • Hellohome option from 10 percent equity

  • Portal for multi-family houses

  • Free rate alert

HYPOPARTNER GmbH

5.036 reviews
Badenerstrasse 47, 8004 Zürich, Switzerland
Best for
Buyers with limited equity

Worth a look for buyers short on equity and for investors financing an apartment building. The broker compares offers from more than 50 banks, insurers and pension funds and supports clients personally up to signing. Through a partnership with Hellohome it can help buyers who have as little as 10 percent of the price in equity. A separate portal covers mortgages for multi-family houses. Founder Dario Sauter spent more than ten years at a Swiss major bank.

Resolve, Zürich#4
What stands out
  • More than 70 financing partners

  • Amortisation and tax advice

  • One adviser from application to signing

Resolve

4.948 reviews
Dianastrasse 9, 8002 Zürich, Switzerland
Best for
Planning amortisation and tax with the loan

A good option for buyers who want amortisation and tax questions settled together with the mortgage. Resolve negotiates with more than 70 financing partners for purchases, renewals and refinancing. A dedicated adviser follows each file from the online application to the signing. It also advises on direct and indirect amortisation through pension savings and on the tax timing of a purchase. The website has an English version, and the Zurich office is on Dianastrasse in Enge.

feyn AG, Zürich#5
What stands out
  • Construction and mixed financing

  • Companies and funds as clients

  • Offices in five Swiss cities

feyn AG

4.927 reviews
Am Schanzengraben 25, 8002 Zürich, Switzerland
Best for
Investment and construction financing

Most useful for complex cases such as construction loans, investment properties or real estate held by a company. feyn arranges purchase, refinancing, construction and mixed financing with third-party lenders across all language regions of Switzerland. Its clients include private buyers, companies and investment funds. Besides Zurich, it has offices in Geneva, Lausanne, Lugano and Basel. The website is available in English.

MoneyPark Zurich#6
What stands out
  • Around 100 providers compared

  • Advisers in many languages

  • Valuation and sale support

MoneyPark Zurich

4.6168 reviews
Hohlstrasse 560, 8048 Zürich, Switzerland
Best for
Many lenders compared in one place

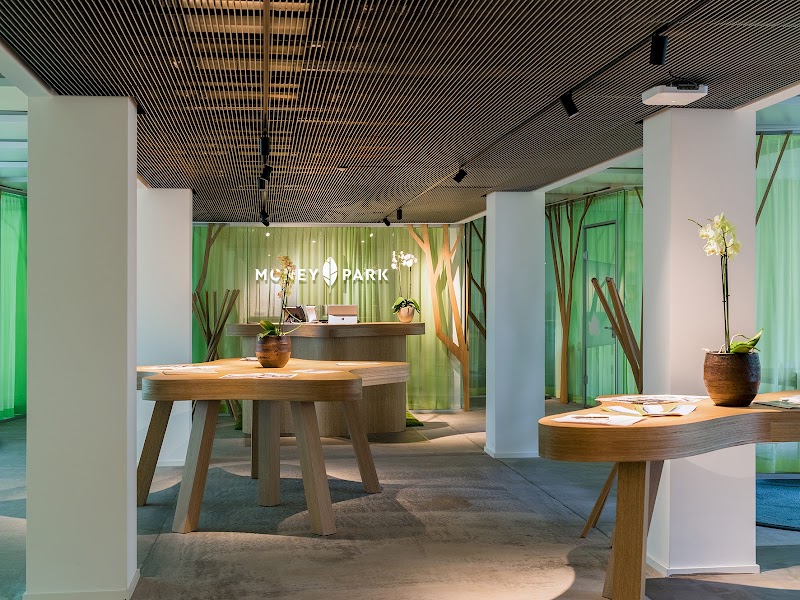
Suits buyers who want a large lender panel and an adviser who speaks their language. MoneyPark compares mortgages from around 100 providers and belongs to the Helvetia insurance group. Its Zurich branch in Altstetten has advisers who work in German, English and Italian, among other languages. Besides financing, the same team values properties and helps owners sell or buyers search. Existing mortgages can be extended through the same advisers.

PVVS Finanzkompetenz, Zürich#7
What stands out
  • From CHF 190 per hour with a cost cap

  • Support up to the notarial deed

  • Tax and pension in-house

PVVS Finanzkompetenz

5.052 reviews
Schaffhauserstrasse 432, 8050 Zürich, Switzerland
Best for
Hourly-billed independent advice

Suits buyers who want mortgage advice from someone who also handles their taxes and pension and bills by the hour. PVVS compares mortgage rates independently of banks, checks affordability and supports clients up to the notarial deed. Advice is charged from CHF 190 per hour with a cost cap. The Oerlikon office also covers pension planning, tax returns and insurance. Meetings can take place by video call as well.

smzh, Zürich#8
What stands out
  • Relocation service for newcomers

  • Pension savings for a home purchase

  • Mortgage check for existing owners

smzh

4.5944 reviews
Tödistrasse 53, 8002 Zürich, Switzerland
Best for
Newcomers combining mortgage, pension and tax

A sensible choice for newcomers who need the mortgage, pension withdrawal and taxes looked at together. smzh is an independent financial adviser with a Zurich office in Enge and a relocation service for people moving to Switzerland. For existing owners it values the property and checks whether the current mortgage still fits. It explains how pension fund and pillar 3a savings can fund a main residence. A free first consultation can be booked online.

VZ VermögensZentrum, Zürich#9
What stands out
  • Mortgage strategy reviewed regularly

  • Reverse mortgage for retirees

  • Rate alarm for fixed terms

VZ VermögensZentrum

4.4358 reviews
Gotthardstrasse 6, 8002 Zürich, Switzerland
Best for
Owners approaching retirement

Fits homeowners close to retirement who want the mortgage planned together with pension, tax and estate questions. VZ develops a mortgage strategy with each client and revisits it at regular intervals. Its rate alarm notifies you when fixed-rate mortgages cross a threshold you set. Retirees can look at a reverse mortgage, and the same firm values and sells properties. The first conversation is free, and the website is available in English.

The comparison at a glance

#BusinessRatingReviewsBest for
#1MY HYPOTHECA AG 5.0227First-time buyers
#2HYPOTHEKE.ch 4.9290Comparing rates online first
#3HYPOPARTNER GmbH 5.036Buyers with limited equity
#4Resolve 4.948Planning amortisation and tax with the loan
#5feyn AG 4.927Investment and construction financing
#6MoneyPark Zurich 4.6168Many lenders compared in one place
#7PVVS Finanzkompetenz 5.052Hourly-billed independent advice
#8smzh 4.5944Newcomers combining mortgage, pension and tax
#9VZ VermögensZentrum 4.4358Owners approaching retirement

Run a business?

Manage or add my business

Map of mortgage brokers in Zurich

Several of these brokers are in Enge between Bahnhof Enge and the lake, with others in Kreis 1, 4 and 5, Altstetten and Oerlikon.

Services to compare

  • Purchase financingComparing offers and preparing the financing file when you buy a flat or house.
  • Renewal and refinancingExtending a maturing mortgage or moving it to another lender at better terms.
  • Choosing the mortgage modelWeighing SARON, fixed-rate and combined mortgages against your plans and risk tolerance.
  • Pension savings and amortisationUsing pension fund or pillar 3a savings for a main residence and planning direct or indirect amortisation.
  • Investment and construction loansFinancing for rental properties, multi-family houses and new builds.

How to choose Mortgage Brokers in Zürich

  1. Ask how the broker is paidMost brokers receive a commission from the lender, some add a platform fee and independent advisers may bill by the hour. Ask whether the commission changes with the lender you choose and whether any of it is passed back to you.
  2. Check who is on the panelA panel can include banks, insurers, pension funds and investment foundations. Ask which lenders the broker actually works with and whether your own bank's offer can be compared on the same terms.
  3. Test affordability earlySwiss lenders usually calculate with a notional interest rate of around 5 percent plus upkeep, and housing costs should stay below about one third of gross income. A broker can tell you your budget before you make an offer on a property.
  4. Mention your permit and plansYour residence permit, nationality and plans to stay can affect which lenders will finance you, and the Lex Koller rules restrict purchases by people living abroad. Raise this at the first meeting.

Frequently asked questions

Do mortgage brokers in Zurich charge a fee?

It depends on the model. Many brokers are paid a commission by the lender and do not bill the client directly, some charge a platform fee that is offset against that commission, and independent advisers often bill by the hour or a fixed amount. Ask for the fee terms in writing before signing a mandate.

How much equity do I need to buy a home in Switzerland?

Lenders generally expect at least 20 percent of the purchase price as equity, and at least half of that must come from sources other than your pension fund, such as savings or pillar 3a. The exact amount you need also depends on the affordability calculation.

What documents should I prepare?

Usually an ID and residence permit, recent payslips or a salary certificate, your latest tax return, an extract from the debt enforcement register, pension fund and pillar 3a statements, proof of equity and the property documents such as the sales brochure, plans and land register extract.

Related guides